Choose a template
Updated September 9, 2026
How to Buy Out a Business Partner
Content
Start with the documents that already govern the exit: a buy-sell agreement, partnership agreement, LLC operating agreement, or shareholder agreement often fixes the valuation method, transfer process, and payment terms before anyone negotiates. Agree on how the business will be valued before arguing about the number, then pick funding the company can service after the exit — cash, a bank or SBA 7(a) loan, or seller financing and installments backed by a promissory note. Write the deal down: price, payment schedule, default rules, liabilities, and transition duties. Then update ownership records, bank signatories, and internal agreements, and chase any third-party consents you need.

Before you discuss price, check what your documents already say.
A buy-sell agreement defines the partner buyout terms, but only if both sides actually follow it. Many disputes arise because partners negotiate from memory rather than reading the agreement.
If there is no buy-sell agreement, the process is often more negotiable. However, it may still be controlled by a partnership agreement, an LLC operating agreement, a shareholder agreement, or default state law. That increases flexibility, but also increases the risk of disagreement. In a partnership, those rules may be set out in the partnership agreement. In an LLC, the operating agreement often controls the transfer process. In a corporation, shareholder agreements, bylaws, and stock transfer restrictions may matter more.
Business valuation determines a fair purchase price, but only when both sides agree on how that price is calculated. For many owners searching how to buyout a business partner, this is the stage where the deal becomes harder, because valuation is often where practical disagreement starts.
Most small businesses use:
Asset-based valuation.
Earnings-based valuation.
Market-based valuation.
Market-based valuation.
A common mistake is using rough estimates or online calculators instead of reviewing real financials. That may be enough for an early discussion, but not for a real ownership transfer.
Choosing a valuation method is usually the easy part. The harder question is how much value the business will actually keep once one partner is gone. An earnings-based approach may overstate value if revenue depends on the departing partner. A market-based approach can be misleading if the business is unusually small, owner-dependent, or lacks stable recurring revenue. An asset-based approach may undervalue a business with strong contracts and client retention, but it may be more realistic if the business is expected to weaken after the exit.
In practice, you almost always need adjustments:
Debt and liabilities.
Inconsistent revenue.
Dependence on one partner.
Customer concentration.
Contracts that may not survive the exit.
This is why valuation disputes often become personal. One side values the business as if operations will continue normally. The other values are based on the disruption the exit may cause. Both sides may sound reasonable, but they can still end up miles apart on price.
At a minimum, review:
Recent profit and loss statements.
Balance sheet.
Debt schedule.
Owner compensation.
Large customer concentration.
Whether important contracts are assignable or likely to continue.
If the number depends on future performance, both sides should be especially careful. Projected growth is easy to argue about and hard to prove. That is why many small business buyouts work better when the parties agree on a valuation method first and only then start debating the assumptions.
Once you agree on value, the next challenge is figuring out how to pay for the buyout without destabilizing the business. For many owners, this is the point where the deal becomes real. The issue is not only in price, but also whether the payment structure will still work after one partner leaves.
Most partner buyouts are funded in one of four ways:
Cash from the buyer or the business.
A bank or SBA-backed loan.
Seller financing.
Installment payments are built into the deal.
A lump-sum payment is the simplest structure, but it requires capital to be available. A loan can preserve working cash, but adds underwriting, repayment obligations, and sometimes collateral requirements. Seller financing can make the deal possible when outside funding is limited, but it also keeps the departing owner financially tied to the business until the balance is repaid. Installment payments can reduce upfront pressure, but they only work when the post-exit business can reliably support them.
In some cases, yes. In the right case, SBA financing funds small business partner buyout deals when the company has the financial strength and documentation to qualify. SBA 7(a) loans can be used for certain ownership changes, and standard bank term loans may also be available, depending on the company’s financial condition and the transaction structure. SBA 7(a) loans are available up to $5 million, and the SBA notes that lenders and borrowers negotiate interest rates subject to SBA maximums. The SBA’s current SOP also makes clear that 7(a) and 504 lending follows detailed origination rules, not a simple one-size-fits-all standard.
In practice, lenders usually want to see more than a signed buyout idea. They often look for:
Strong business financials.
Enough cash flow to service the new debt.
A credible valuation.
Clean tax and accounting records.
Collateral or other credit support in some cases.
A buyer with acceptable credit and management experience.
Traditional bank loans can work for stronger businesses that already have a banking relationship, steady revenue, and documentation that supports repayment. Online lenders and other nonbank lenders may be faster or more flexible, but they often come with higher borrowing costs. Business lines of credit are also common, but they are usually a better fit for short-term working-capital needs than for funding a full partner buyout.
When the ownership changes, the agreement must be written. There are often disagreements later on about what the price included, when payments were due, who was responsible for certain tasks, or what kind of help the partner who is leaving was supposed to provide after the deal is done.
Your buyout agreement should clearly define:
The ownership interest is being transferred.
Purchase price.
Payment terms.
Default rules.
Liabilities.
Transition responsibilities.
This is the stage where the deal moves from discussion to enforceable terms. Instead of drafting from scratch, a business purchase agreement helps you structure ownership transfer, payment terms, and liability allocation in a way that is easier to enforce.
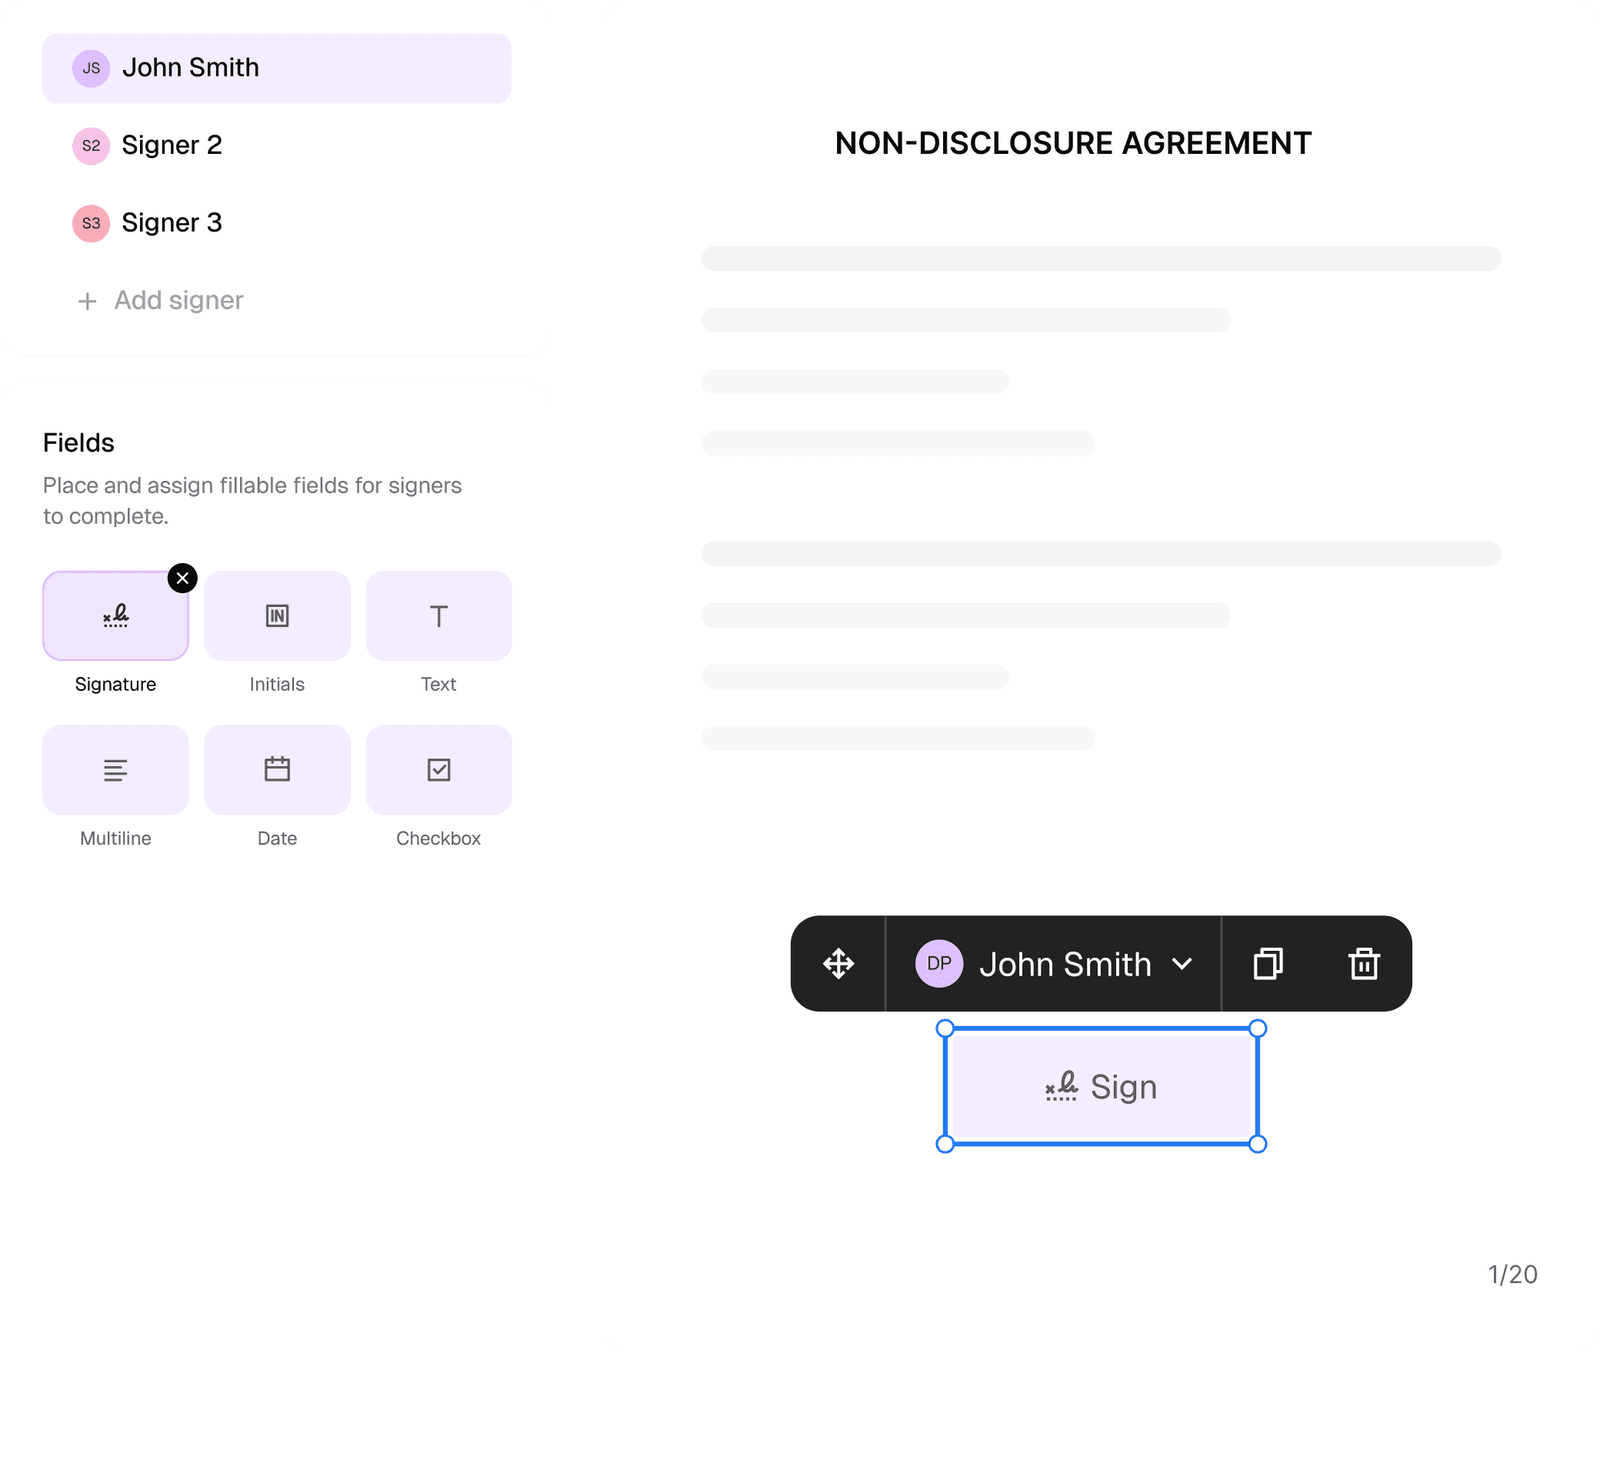
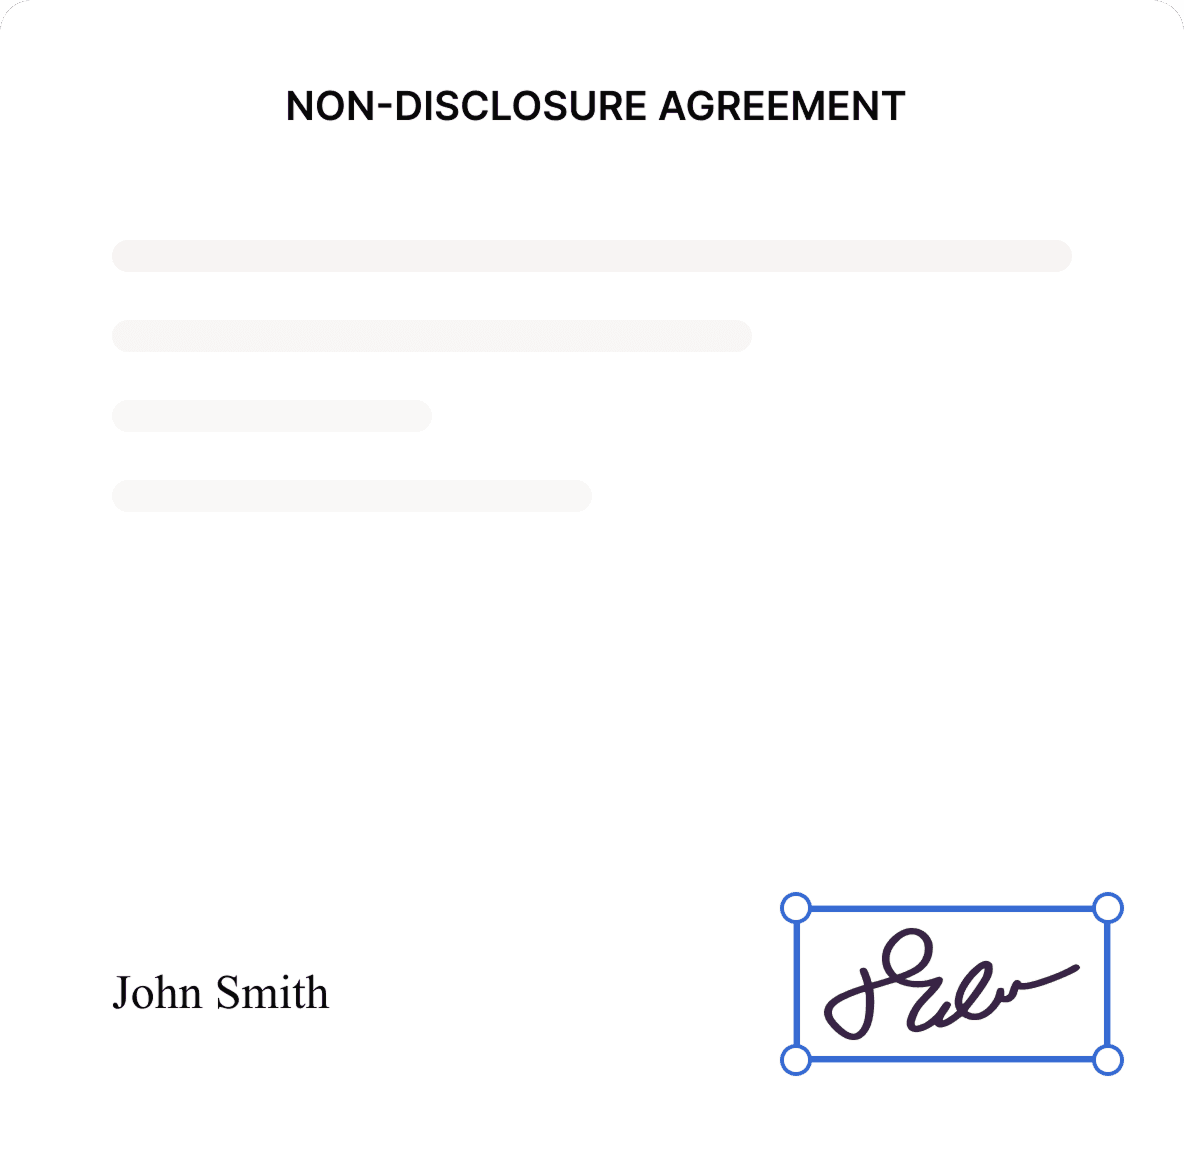
Once terms are agreed, eSign helps finalize the deal quickly while both sides are aligned, rather than letting it stall in emails or drafts.
Many buyers focus so heavily on the buyout price that they miss the liabilities that stay with the business after the deal closes. That is where many “fair” deals later turn sour.
Before signing, review:
Business debt.
Leases.
Personal guarantees.
Unpaid invoices.
Vendor contracts.
Customer obligations.
The key question is which obligations will still follow the business after the ownership change, and whether the departing partner is actually being released from them.
A buyout does not automatically remove these risks. If a partner guaranteed a loan, signed a lease, or personally backed another obligation, that responsibility may continue unless the lender, landlord, or other third party formally agrees to a change. In practice, that means you may need to:
Identify which debts or contracts are personally guaranteed.
Review whether the agreement allows assignment, assumption, or release.
Ask the lender, landlord, or contract counterparty for the required approval.
Document in the buyout agreement who remains responsible if a third party refuses to release the exiting partner.
Decide whether part of the purchase price should be adjusted to reflect those unresolved liabilities.
This matters because buyers and sellers often assume that signing the buyout agreement will cleanly separate their obligations. In reality, outside parties are not bound by that assumption. A lender may still expect the original guarantor to remain liable. A landlord may refuse to release a partner from a lease, especially if the commercial lease agreement requires written consent before any assignment, transfer, or change in control. A vendor or customer contract may also require consent before the business can transfer rights or responsibilities under the agreement.
Before closing, the parties should prepare a clear list of the liabilities that remain with the business, those that require third-party approval, and the risks that must be allocated between the buyer and the departing partner if no release is obtained.
The deal is not finished when the payment is made. You still need to update:
Ownership records.
Bank accounts.
Internal agreements.
Licenses.
Vendor relationships.
This is where the ownership change starts to affect the business in practice, not just on paper. Some buyouts only require internal updates, such as revising the partnership agreement, LLC operating agreement, shareholder records, ownership ledger, or internal resolutions. Hence, they reflect the new ownership and control structure. Other buyouts also affect outside records and third-party relationships.
Depending on the entity type and the way the transfer is documented, the business may need to update state registration records, licenses, tax reporting, bank signatory authority, insurance records, and contracts that restrict assignment or changes in control.
In practice, that may also mean contacting the bank to remove or add authorized signers, updating responsible-party information with the IRS on Form 8822-B if it has changed, and checking whether the ownership change triggers any new EIN issue under IRS rules.
Legal help is not always required for every update, but it becomes much more important when the transfer affects entity structure, third-party consents, leases, guarantees, or tax treatment.
If you skip this step, the former partner may still appear on accounts or documents, which creates risk later.
After the buyout, your internal documents must reflect the new ownership. Updating your LLC operating agreement or partnership agreement ensures decision-making, profit distribution, and control are aligned with the new structure.
Disagreements over price are common. They usually happen because:
The partners did not agree on the valuation method.
Assumptions differ.
Financial records are unclear.
At this stage, partners often need to share detailed financial records, client data, and internal projections. If the relationship is already strained or third parties are involved, it may be worth documenting confidentiality expectations upfront. A simple non-disclosure agreement (NDA) can help protect sensitive business information while valuation and buyout terms are being discussed.
The paperwork is for most buyouts to go through, and they fail because the company can't handle the change in real life. The biggest mistakes are:
Rushing the deal.
Skipping agreement review.
Weak valuation.
Ignoring liabilities.
Vague payment terms.
There are also emotional mistakes:
Negotiating out of frustration.
Trying to “win” the deal.
Avoiding clear terms just to keep things friendly.
And operational mistakes:
No transition plan.
No update of accounts.
No review of guarantees.
No cash flow check.
A partner buyout fails when the deal looks good on paper but does not work in reality.
A useful way to test the deal before signing is to ask one final question: Will this still work six months after closing if revenue dips, a client leaves, or the transition takes longer than expected? If the answer is no, the deal may be too fragile.
That is why the best buyouts are not just legally documented. They are financially realistic, operationally workable, and clear enough that neither side has to guess what happens next.
September 1
7 min read
How to Provide Proof of Employment: Documents and Steps
August 20
How to Start a Staffing Agency: Licensing, Pricing, and Cash Flow
July 20
4 min read
Addendum vs. Amendment: Change Your Purchase Agreement Properly
July 20
What Is an Assignment of Contract? Rights, Duties, and Consent
September 9
9 min read
How to Liquidate a Company

July 21
8 min read
Statement of Work vs Scope of Work: Differences and How They Work Together
Tweak agreements before signing or sending for signatures. Update details, add or remove clauses, adjust formatting, and redline changes instantly.
Sign documents and collect legally binding signatures. Invite up to ten people to sign in any order, track the progress, and send reminders.
Invite up to ten people to sign your document in any order. Get a finalized, audit-ready copy without chasing signatures.