Updated July 22, 2026
8 min read
How To Get a Startup Business Loan with No Money

How To Get a Startup Business Loan with No Money
Content
Launching a business is exciting, but financing can be tricky — particularly when you lack income. Most lenders require evidence that your business generates revenue before granting a loan. But what if your company hasn't begun generating income yet? The positive aspect is that you can still obtain funding effectively. The essential approach is to showcase your business persuasively, investigate different funding alternatives, and confirm you possess the required paperwork.
This article will discuss how to obtain startup business loans with no revenue and the actions you should follow to enhance your likelihood of getting approved.
How Startup Business Loans Work
A business loan with no revenue is intended for startups without a history of financial performance. They don’t depend on income but emphasize your business's potential and financial condition.
Higher risk for lenders. Since your business isn’t generating income yet, lenders take on more risk when funding you.
Approval criteria differ. Rather than focusing on business income, lenders will evaluate factors such as your credit rating, business strategy, sector, and individual finances.
A strong application is key. Even without income, a solid business plan, good credit, and thorough preparation can significantly improve your chances of getting approved.
If you have a startup, smaller banks are a better option for funding. Around 66% of small banks lend to startups, while only 54% of large banks do. Big banks rely more on credit scores, making approval harder for new businesses.

Overcoming the Challenge of No Capital
Convincing lenders to fund your business without existing capital is no small task. Without revenue, they need to see other signs of financial security. How to get a startup business loan with no money?
- Highlight your business potential. Use market research, demand analysis, and projected revenue to show that your business will soon generate income.
- Leverage personal credit. Because your business lacks a credit history, lenders will depend on your credit score. A high score (700+) can benefit you.
- Show alternative income sources. A side job, freelance work, or other steady income reassures lenders that you can make regular loan payments.
- Look into alternative funding. Some lenders specialize in startup funding without requiring immediate revenue. Consider online lenders, microloans, crowdfunding, or venture capital.
- Offer collateral or a cosigner. Pledging personal assets or having someone with good credit cosign your loan can significantly improve your chances of approval.
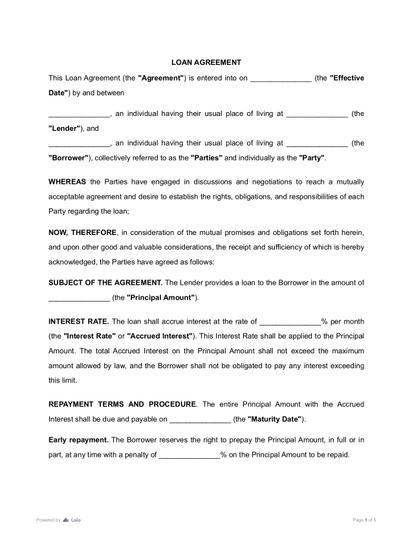
Having a prepared Loan Agreement Template can simplify the lending process. This document details repayment plans, interest rates, and other critical information.
Preparing for a Successful Loan Application
How to get a business loan with no revenue? Preparation is everything. Before applying, ensure you have a well-structured plan and all required documents.
1. Build a solid business plan
A thoughtfully designed business plan demonstrates to lenders that you possess a clear path to profitability. Be sure to include:
- Summary for executives. A summary of your company, its objectives, and market potential.
- Market analysis. Data on your target audience, competition, and demand for your product or service.
- Revenue model. A breakdown of how your business plans to generate income.
- Operational plan. This is how your company will function daily.
- Funding request. The amount you need, why you need it, and how you will use the funds.
2. Strengthen your credit score
Lenders will assess your credit since your business is new. Here’s how to improve your score before applying:
- Pay down existing debts. A lower debt-to-income ratio boosts your creditworthiness.
- Make all payments on time. Late payments damage credit history.
- Check your credit report. Dispute any inaccuracies that could be reducing your score.
Requesting more than one no money down business loan or numerous credit cards may negatively impact your rating.
3. Consider collateral or a personal guarantee
Using assets like property or equipment as collateral improves your chances of approval. Some lenders may require a personal guarantee if you don't have collateral.
Personal guarantees can be risky. Only agree if you’re confident in repaying the loan.
Types of Startup Loans
Now that your application is strong, what are your financing options?
1. SBA Loans (Small Business Administration Loans)
- Backed by the U.S. government;
- Lower interest rates and longer repayment terms;
- Requires good credit and a solid business plan.
2. Microloans
- Ideal for startups needing between $500 – $50,000;
- Offered by nonprofit organizations;
- Easier qualification compared to traditional bank loans.
3. Business Credit Cards & Lines of Credit
- Quick access to funds;
- Helpful in covering small expenses;
- Some credit cards offer 0% APR introductory offers.
4. Crowdfunding & Alternative Lending
- No repayment is required (for donation-based crowdfunding);
- Direct financial support from future customers and investors.

How To Apply — and Get Approved
You're ready to apply for the starting business loan! What steps can you take to increase your chances of approval?
- 1
Gather all necessary documents. Have your business plan, credit reports, income details, and funding requirements ready.
- 2
Choose the right lender. Some lenders are supportive of startups, whereas others concentrate on established companies.
- 3
Write a compelling application. Highlight your business potential, projected revenue, and repayment plan. Make it clear why you’re a viable applicant.

What If You Get Denied?
Being rejected doesn’t mean it's over. Instead of giving up, take these steps:
- Ask for feedback. Understanding why you were denied helps you fix weak areas.
- Address weaknesses. If your credit score is low, work on improving it. If your business plan is weak, add more details.
- Try different lenders. Funding sources vary. Consider online lenders, microloans, or crowdfunding options.
Numerous thriving companies faced challenges in obtaining funding before finding investors.
Final Thoughts
Getting no revenue business loans is challenging but achievable. Enhance your credit, develop a robust business plan, and investigate funding alternatives to boost your chances. Every thriving business has to begin at some point — don’t allow insufficient funds to hold you back! Using the correct strategy, you can obtain the funds needed to realize your concept.
More guides
July 25
12 min read
How to Register a Company in the US: What No One Tells You in 2026
September 1
7 min read
How to Provide Proof of Employment: Documents and Steps
August 20
How to Start a Staffing Agency: Licensing, Pricing, and Cash Flow
July 25
12 min read
How to Start a Flooring Business and Get Your First Clients in 2026
September 7
8 min read
A Comprehensive Guide to Starting a Child Care Business
July 22
10 min read
How to Start a Storage Unit Business: What You Need to Know
One home for your
agreements
Edit PDFs seamlessly
Tweak agreements before signing or sending for signatures. Update details, add or remove clauses, adjust formatting, and redline changes instantly.
eSign legally and securely
Sign documents and collect legally binding signatures. Invite up to ten people to sign in any order, track the progress, and send reminders.
Request legally binding signatures
Invite up to ten people to sign your document in any order. Get a finalized, audit-ready copy without chasing signatures.
Skip the drafting.
Choose from 2,500+ templates
Browse templatesChoose a template
Fill in details
Sign and download