Step 1: Review the lease before you sell
Before you negotiate with a buyer or set a closing date, start with the lease itself. Your lease often determines whether the business sale can move forward smoothly — or stall completely. To save time, you can use AI summary tools to quickly identify assignment clauses, consent requirements, and personal guarantees before doing a deeper review.
Review these key sections carefully:
- Assignment and consent clauses
This section explains whether you’re allowed to transfer the lease at all and whether landlord approval is required. Some leases allow assignment only with consent, while others prohibit it entirely. Knowing this early helps you avoid signing a deal you can’t legally complete.
- Change-of-ownership language
Many leases treat a business sale — especially a sale of ownership interests — as a lease “assignment,” even if the tenant name stays the same. This means landlord consent may still be required even if the business entity doesn’t change.
- Personal guarantees
If you personally guaranteed the lease, selling the business does not automatically release you from liability. Without a written release from the landlord, you could remain responsible for rent and damages long after the sale.
- Default triggers related to a sale
Some leases define a sale or transfer as a potential default if not handled correctly. Missing notice requirements or closing before approval can trigger penalties or even lease termination.
Why this step matters
First-time sellers often assume the lease will “sort itself out later.” In reality, lease terms can limit buyer options, reduce the purchase price, or delay closing by months.
Step 2: Understand the landlord consent process
Landlord consent is a legal requirement. Even if you’ve already found a buyer, the lease usually cannot be transferred unless the landlord formally approves the new tenant in writing.
For someone going through this process for the first time, it helps to know what landlords actually look at. In most cases, the landlord will review the buyer’s financial stability, business experience, and ability to meet rent and lease obligations. This often includes requesting financial statements, credit information, or details about how the business will operate in the space.
Timing is another common surprise. Landlord approvals are rarely instant. Many leases allow landlords 15–30 days (or longer) to review an assignment request after receiving complete documentation. If documents are missing or incomplete, the review period often resets, causing delays.
It’s also important to understand that consent may come with conditions. Landlords sometimes require additional security deposits, personal guarantees, or amendments to the lease terms as part of the approval. These conditions can affect both the deal structure and the final purchase price.
A landlord usually evaluates:
- Buyer’s financial strength;
- Credit history;
- Business experience;
- Fit with the property.
Landlords typically request:
- Financial statements;
- Credit reports;
- Business background;
- Draft transfer documents.
To ensure the buyer is legally prepared for this review, advise them to follow our guide on how to register a business in the U.S. to verify their new entity is active and compliant before the landlord starts their due diligence.
Step 3: Tenant checklist for transferring the lease
If you are the current tenant selling the business, the lease transfer process should follow a clear order. Skipping or rushing steps is one of the most common reasons sellers remain legally and financially liable after closing.
1Confirm the lease allows assignment
Start by reviewing your lease to see whether assignment or transfer is permitted at all. Some leases prohibit assignment entirely, while others allow it only with landlord approval. Knowing this upfront prevents wasted negotiations with buyers.
2Identify the landlord’s consent requirements
Most commercial leases require the landlord’s written consent before a transfer. The lease often specifies what the landlord can ask for — such as financial statements, business experience, or personal guarantees from the buyer. Understanding these requirements early helps you set realistic timelines.
3Collect the buyer’s financial information
Landlords usually evaluate the buyer’s ability to pay rent. Be prepared to collect documents like financial statements, tax returns, or credit information from the buyer. Delays here are one of the most common causes of stalled approvals.
4Submit a formal approval request
Verbal discussions aren’t enough. Most landlords require a written request that includes the buyer's details, the proposed transfer date, and supporting documents. Submitting a complete package increases the chance of faster approval.
5Prepare the lease transfer documents
Depending on the lease, this may involve an assignment agreement, assumption agreement, or landlord consent form. These documents define who is responsible for the lease going forward and on what terms.
6Align landlord approval with the closing date
Lease approval should be obtained before closing or clearly tied to it as a condition. Closing without approval can leave the seller responsible for rent even after selling the business.
7Confirm whether liability is fully released
Some leases allow assignment but keep the original tenant liable if the new tenant defaults. If possible, negotiate a release of liability, so you’re not responsible for future rent or damages after the transfer.
Skipping steps is one of the most common reasons sellers remain liable after closing.
Step 4: Use the right contract documents
A lease transfer only becomes legally effective when the right documents are signed and aligned. Verbal agreements or emails are not enough. In most commercial transactions, the transfer depends on a small set of contracts, each with a specific role.
A lease assignment agreement (transferring rights and obligations).
This is the core transfer document. It formally moves the lease rights and obligations from the current tenant to the new tenant. It defines who takes over rent payments, maintenance duties, and compliance with lease terms from the effective date. Without a properly executed assignment agreement, the original tenant may remain fully responsible for the lease — even after selling the business.
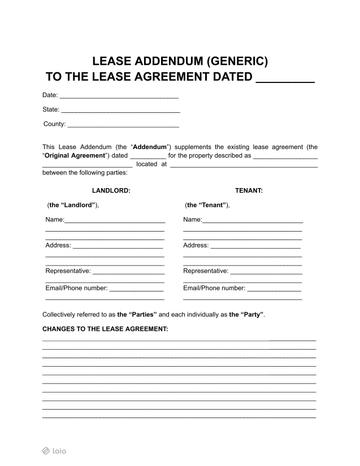
A landlord consent addendum (approving the transfer).
This document is the landlord’s written approval of the transfer. It confirms that the landlord agrees to the new tenant and often sets conditions, such as guarantees or updated lease terms. Without this consent, the assignment may be invalid, and closing without it can trigger default under the lease.
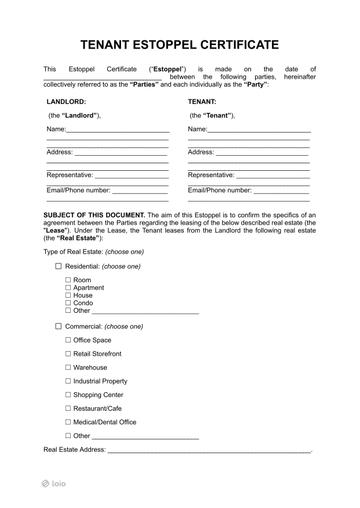
An estoppel certificate (confirming lease status).
An estoppel certificate is the landlord’s confirmation that the lease is in good standing. It states key facts such as the current rent, remaining term, and whether any defaults exist. Buyers rely on this document to confirm there are no hidden issues that could affect the business after closing. In 2026, the estoppel certificate should explicitly confirm that all tax pass-throughs and CAM reconciliations for the prior year are finalized.
Step 5: Coordinate the lease transfer with closing
Lease transfer approval shouldn’t be an afterthought — it should be coordinated directly with the sale closing. In practice, this means the landlord’s written consent is obtained before closing or clearly listed as a condition that must be satisfied at closing. Without this, ownership of the business may change hands while the lease legally stays behind, creating serious risk for both sides.
When lease issues aren’t addressed early, several problems commonly arise:
Deals take longer to close.
Landlords often require financial reviews, background checks, or additional documentation from the buyer. If this process starts late, it can stall the entire transaction.
Buyers renegotiate or walk away.
If lease approval becomes uncertain near closing, buyers may lower their offer, delay payment, or exit the deal altogether to avoid being stuck without a location.
Sellers remain liable longer than expected.
Until the landlord formally approves the transfer, the seller is often still legally responsible for rent, damages, or lease violations — even after selling the business.
Treat lease approval like financing or licenses — something that must be cleared before closing, not after. Build landlord consent into your closing checklist and timeline so the deal doesn’t depend on last-minute approvals.